

You make your final payment, your balance hits zero, yet your credit score drops.
It seems odd, but this is a common question our lenders hear. Decades of analyzing credit reports show it happens often. The key is understanding what has changed with your profile, not your financial health. Below, we explain the reasons behind the score drop and why it's not cause for concern.
Paying Off a Loan Is Still a Financial Win
Seeing your credit score dip after paying off a loan can make it feel like you've been penalized for doing the right thing. In reality, the opposite is true. Paying off debt lowers what you owe, demonstrates healthy borrowing, and fulfills the commitment you made when you took out the loan. Those are all positive outcomes that lenders appreciate.
The confusion often comes from how credit scores are calculated. Credit scoring models aren't designed to celebrate milestones like paying off a loan. Instead, they're constantly evaluating the makeup of your current credit profile. Once that loan is closed, your profile changes, and your score may adjust accordingly. If you're curious about the factors behind those changes, our How Credit Scores Are Calculated Guide explains how payment history, credit utilization, account age, credit mix, and new credit all influence your score.
Your Credit Mix Just Changed
One of the biggest reasons for a temporary dip is something called credit mix. Credit scoring models generally like to see borrowers successfully managing different types of credit, such as installment loans and revolving accounts. An auto loan, mortgage, or personal loan is considered an installment loan, while credit cards are considered a form of revolving credit.
Your Active Accounts Carry More Weight
When a loan closes, it is no longer considered an active account. While paid loans typically remain on your credit report for years and keep contributing positive payment history, scoring models place greater emphasis on accounts that are currently open and being managed. If your remaining accounts have higher balances or shorter histories, they now represent a larger share of your overall credit profile.
Average Account Age Can Shift Over Time
Also, be aware that while they carry less weight, a paid off loan doesn't disappear immediately. Closed accounts in good standing generally remain on your credit report for years.
Eventually, when that account ages off your report, your average account age may decrease. Older credit histories generally demonstrate sustained financial soundness, so losing an established account can have a modest impact years later. This isn't an immediate effect after payoff, but it's another reason credit scores naturally fluctuate over time.
Look Beyond the Numbers
One lesson we've learned over decades of lending is that borrowers often focus on a single credit score, while lenders look at the bigger picture. A paid-in-full loan indicates you borrowed responsibly, made your payments, and fulfilled the agreement. That's meaningful information that a temporary change of a few points doesn't erase.
Credit scores are designed to fluctuate. What matters most is the habits behind them. Consistently paying on time, keeping balances under control, and using credit responsibly have a much greater impact over time than any short-term movement after paying off a loan.
Know Where You Stand
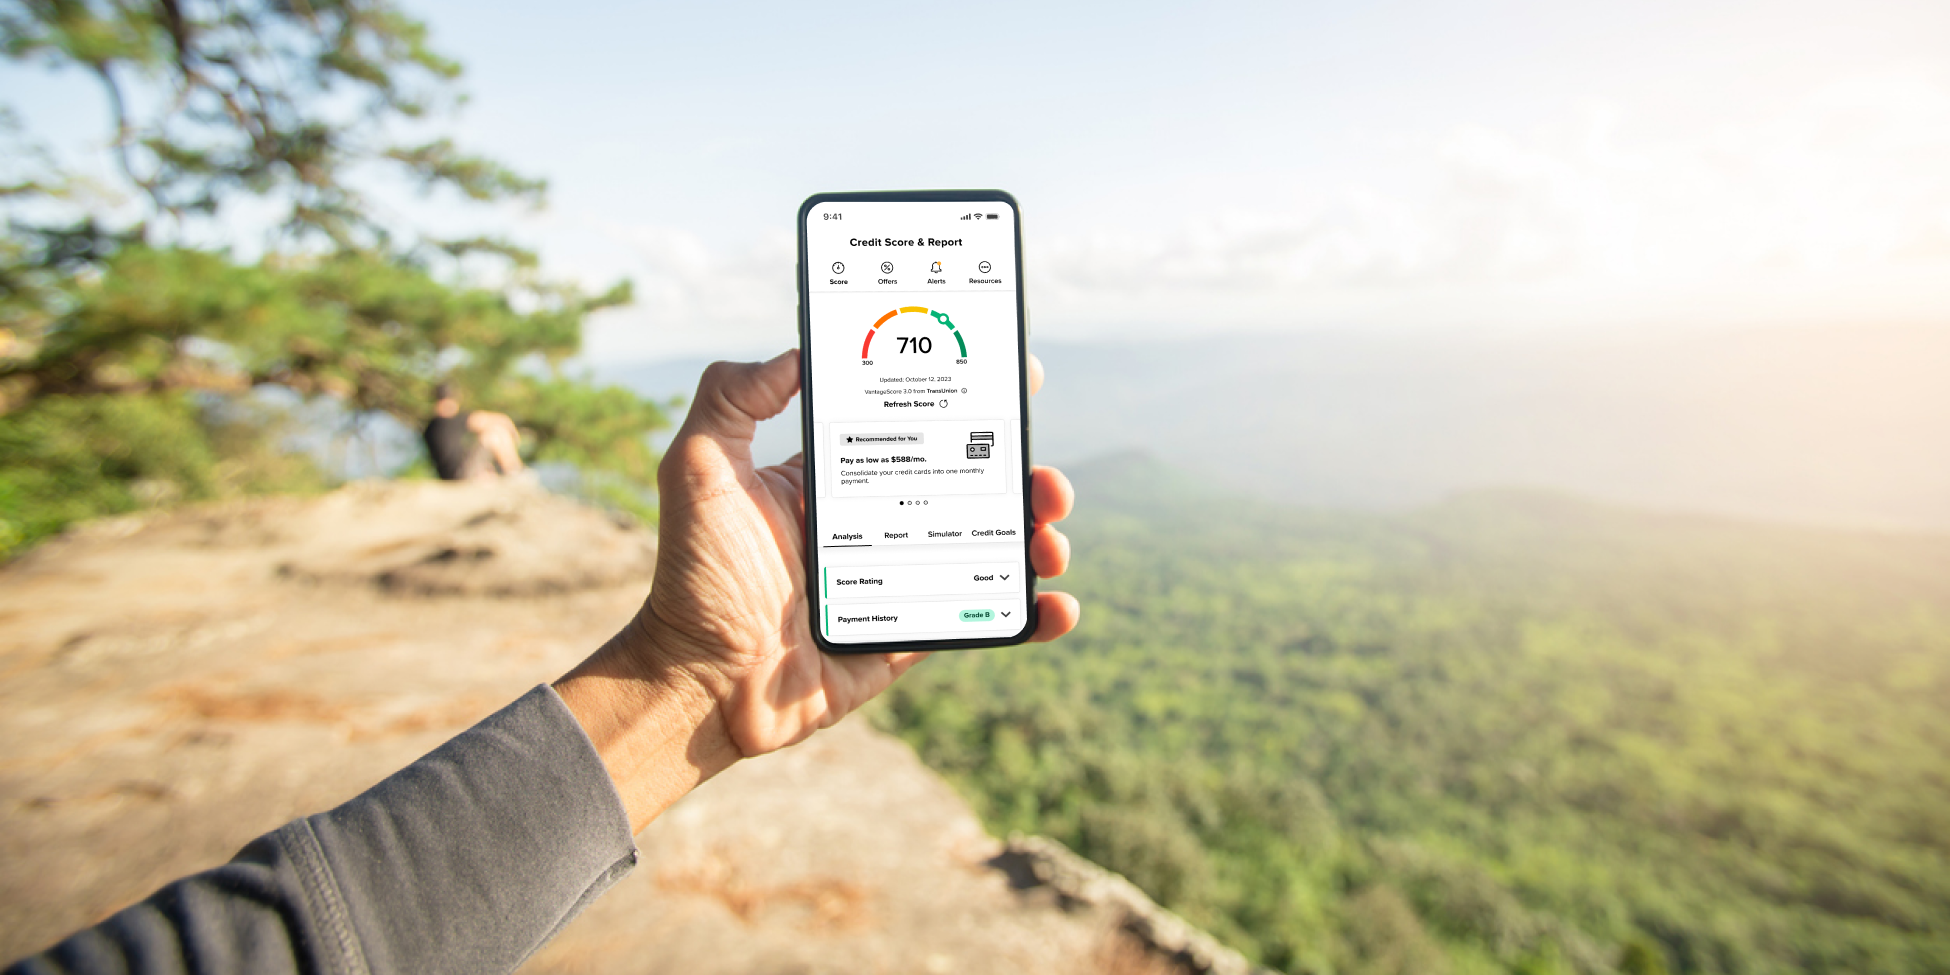
Your credit score should be a tool, not a surprise. Vermont Federal Credit Union members can monitor their credit score anytime through Online Banking and Mobile Banking, making it easier to understand how everyday financial decisions affect their credit. Whether you're getting ready to purchase a home, finance your next vehicle, or want to strengthen your financial future, our local lending team is here to help you understand your options with confidence. Because at Vermont Federal, we believe better financial decisions start with understanding the story behind the numbers.